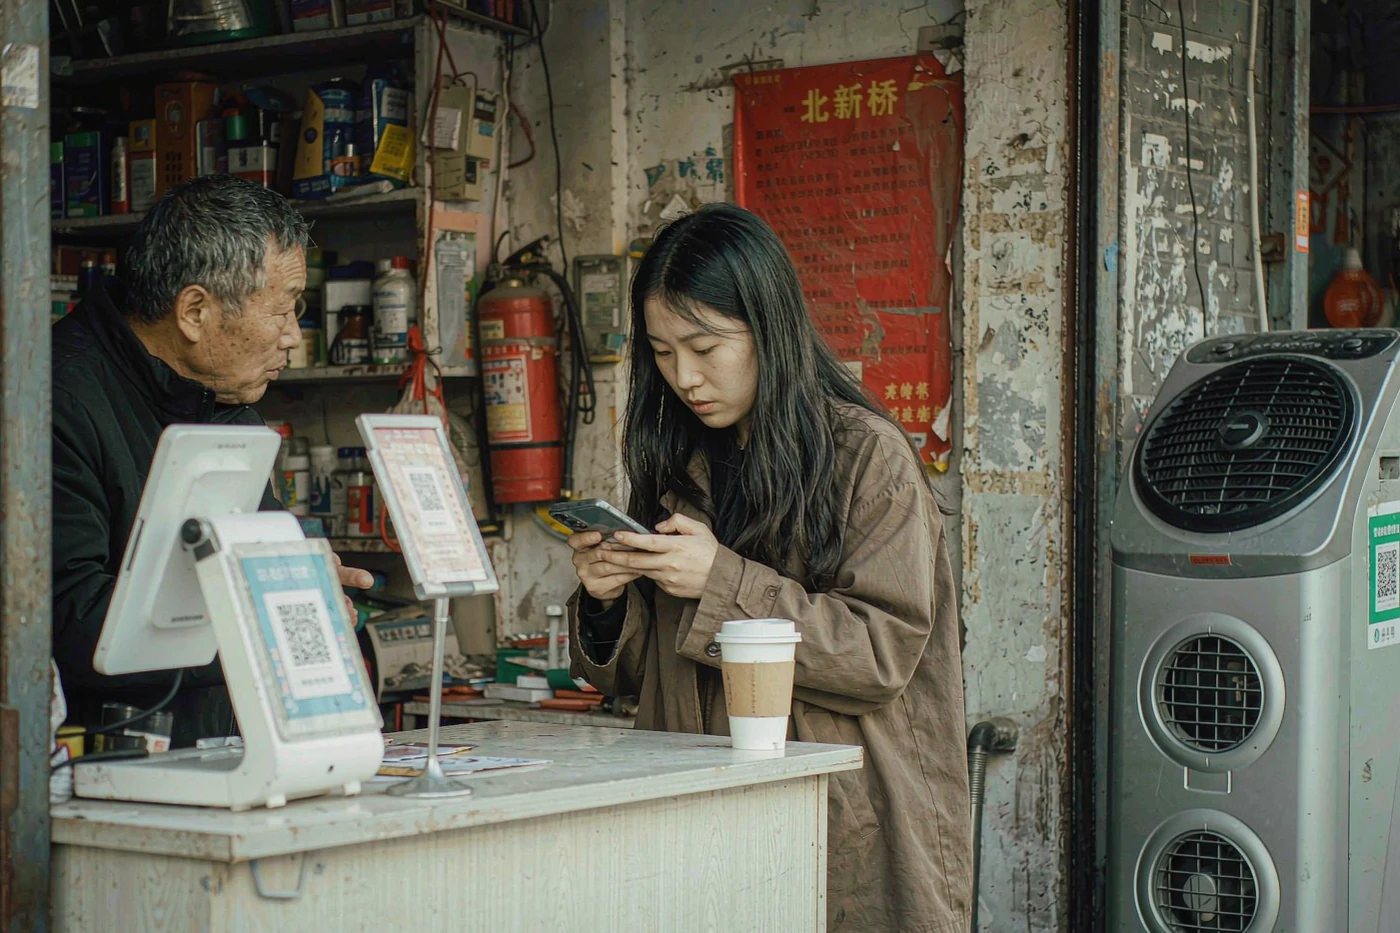
Scanned the wrong QR or typed the wrong amount? The exact recovery steps for WeChat Pay and Alipay, the hotlines to call, and the settings that protect you next time.
Almost every foreign visitor in Beijing pays by QR code, and sooner or later one payment goes sideways: you typed 2,135 instead of 21.35, you scanned a code that turned out to be a personal account, or a sticker over the real merchant code routed your money somewhere else. The good news is that a wrong mobile payment in China is usually recoverable, if you act within hours and follow the official channels. The bad news is that nothing reverses instantly by itself — every path runs through the app's complaint system, a phone hotline, or the police. This guide walks through each scenario in the order you should actually try them.
The recovery route depends entirely on who received your money, so spend one minute sorting the situation before touching any buttons. The three cases below have different levels of difficulty, and the first one is genuinely easy.
If the money simply went to the shop in front of you, the merchant can refund it directly to your original payment method, and the overwhelming majority do exactly that once you show the receipt. Open the transaction record, tap the payee profile card, and either talk to the staff in person or send a message through it. Show the amount on your screen and the wrong entry in your bill; the merchant initiates a refund on their side and the money returns by the same route it came. When language is a barrier, showing the transaction and saying 'refund, duō le' (overpaid) usually works. In one widely reported Beijing-area case a customer overpaid more than 21,000 yuan for four baozi, and the shop owner called the police to find him and return the money.
WeChat's official position is blunt: a completed transfer cannot be revoked by the sender. But the app gives you two levers. If the recipient has not yet accepted the money, ask them to tap 'Immediately return' — refunds come back in real time from wallet balances, or within a few working days for bank-card funded transfers. If they have taken the money, go to Me → Services → Wallet → Bills, open the transaction, and tap 'I have questions about this order' to file a complaint with your evidence attached; approved complaints let the platform freeze the recipient's account and payment privileges. Call the WeChat Pay hotline 95017 and say plainly that it was a wrong payment; overseas callers dial +86 571 95017.
Alipay mirrors the same logic. The bill detail page carries a contact and complaint entry for the counterparty, and the platform's only official hotline is 95188. For personal transfers the recipient sees the money only after accepting it, so a mistaken transfer that has not been accepted can still be politely requested back, and Alipay customer service can, within legal limits, help contact the recipient on your behalf. Both apps respond far faster to a specific transaction number than to a general story, so have the exact time, amount and payee name ready before you call.
When a stranger who received your money stops responding or blocks you, stop negotiating and go official. Call 110 (or the anti-fraud line 96110) with the transfer time to the minute, the amount and the recipient's account; police can trigger emergency payment stops that freeze the receiving account. File the in-app complaint at the same time — platforms can freeze accounts on their own once a complaint is verified. Under Chinese civil law, money transferred by mistake is unjust enrichment and the recipient is obliged to return it, and courts do enforce this; the practical route for foreigners is usually police mediation rather than a lawsuit, which must be filed where the recipient lives. One hard rule: anyone online who messages you claiming to be a 'recovery specialist' is running a second scam — all recovery runs through the apps' official channels and the police only.
The classic street version of a wrong payment is a personal QR sticker pasted over a shop's real code. Your money lands in a stranger's account, and the merchant never received it. The catch is simple: both apps show the payee's name on the confirmation screen before you authorize, and a legitimate merchant code displays the shop's registered name, while a personal code shows an individual's name. Glance at that name every single time. Also confirm the amount on the same screen, since rushed fingers cause more overpayments than thieves do. If you realize you paid a fake code, treat it as the fraud case above — report to the merchant, the platform, and the police, since the merchant is also a victim and often reports it simultaneously.
Both apps offer a delayed-transfer setting that buys you an undo window. In WeChat it lives under payment settings as 'transfer arrival time' with 2-hour or 24-hour options; in Alipay it is the delayed transfer service with the same two windows. Money sent with the delay sits pending until the recipient accepts and the timer runs out, and if you report a problem before arrival, the platform can freeze the transfer and, with police confirmation of fraud, return it. It does not make you immune — an honest wrong payment still needs the normal complaint process — but it converts a panic moment into a solvable one. Tourists who handle larger transfers, such as paying a landlord, should switch it on.
Every channel — app complaint, hotline, police station — moves faster with clean evidence, and some of it is only easy to capture immediately. Save the transaction serial number from the bill detail, full-screen screenshots of the payment record, the recipient's account name and any chat messages, and ask WeChat for the transfer electronic voucher, which carries legal weight as documentation. Keep your phone unlocked for the police officer, not for strangers: if anyone asks to borrow your phone to scan their own code, that is a known scam, not an emergency.
Set expectations correctly and the process is less frustrating. Neither app can pull money back from a stranger's account on your say-so, and neither compensates you for your own typing mistake. What they can do is freeze a recipient's account after verifying your complaint, help contact the recipient within legal limits, and cooperate fully with police and courts. Police can issue emergency payment stops for fraud and mediate disputes. Refunds of any kind return by the original route, so money paid from an internationally bound card goes back to that card, typically within days rather than seconds [verify]. If a large sum is genuinely withheld, a small-claims civil action on unjust-enrichment grounds succeeds routinely in Chinese courts — but as a visitor you will almost never get that far.